The Quirky Math of Partnership Income

Aug 2, 2025 | Business, Newsletter, Tax

When it comes to taxation, partners in a business may find the math a bit puzzling. You may discover that the amount of partnership income you’re taxed on is more than the amount that was distributed to you. That’s a quirk of taxation that lies in the way partnerships and partners are taxed.

Pass-Through Taxation

Partnerships aren’t subject to income tax at the entity level. Instead, each partner is taxed on the earnings of the partnership, even if the profits aren’t distributed.

Similarly, if a partnership incurs a loss, it’s passed through to the partners. (However, various rules may prevent partners from currently using their shares of the partnership’s losses to offset other income.)

Filing Responsibilities

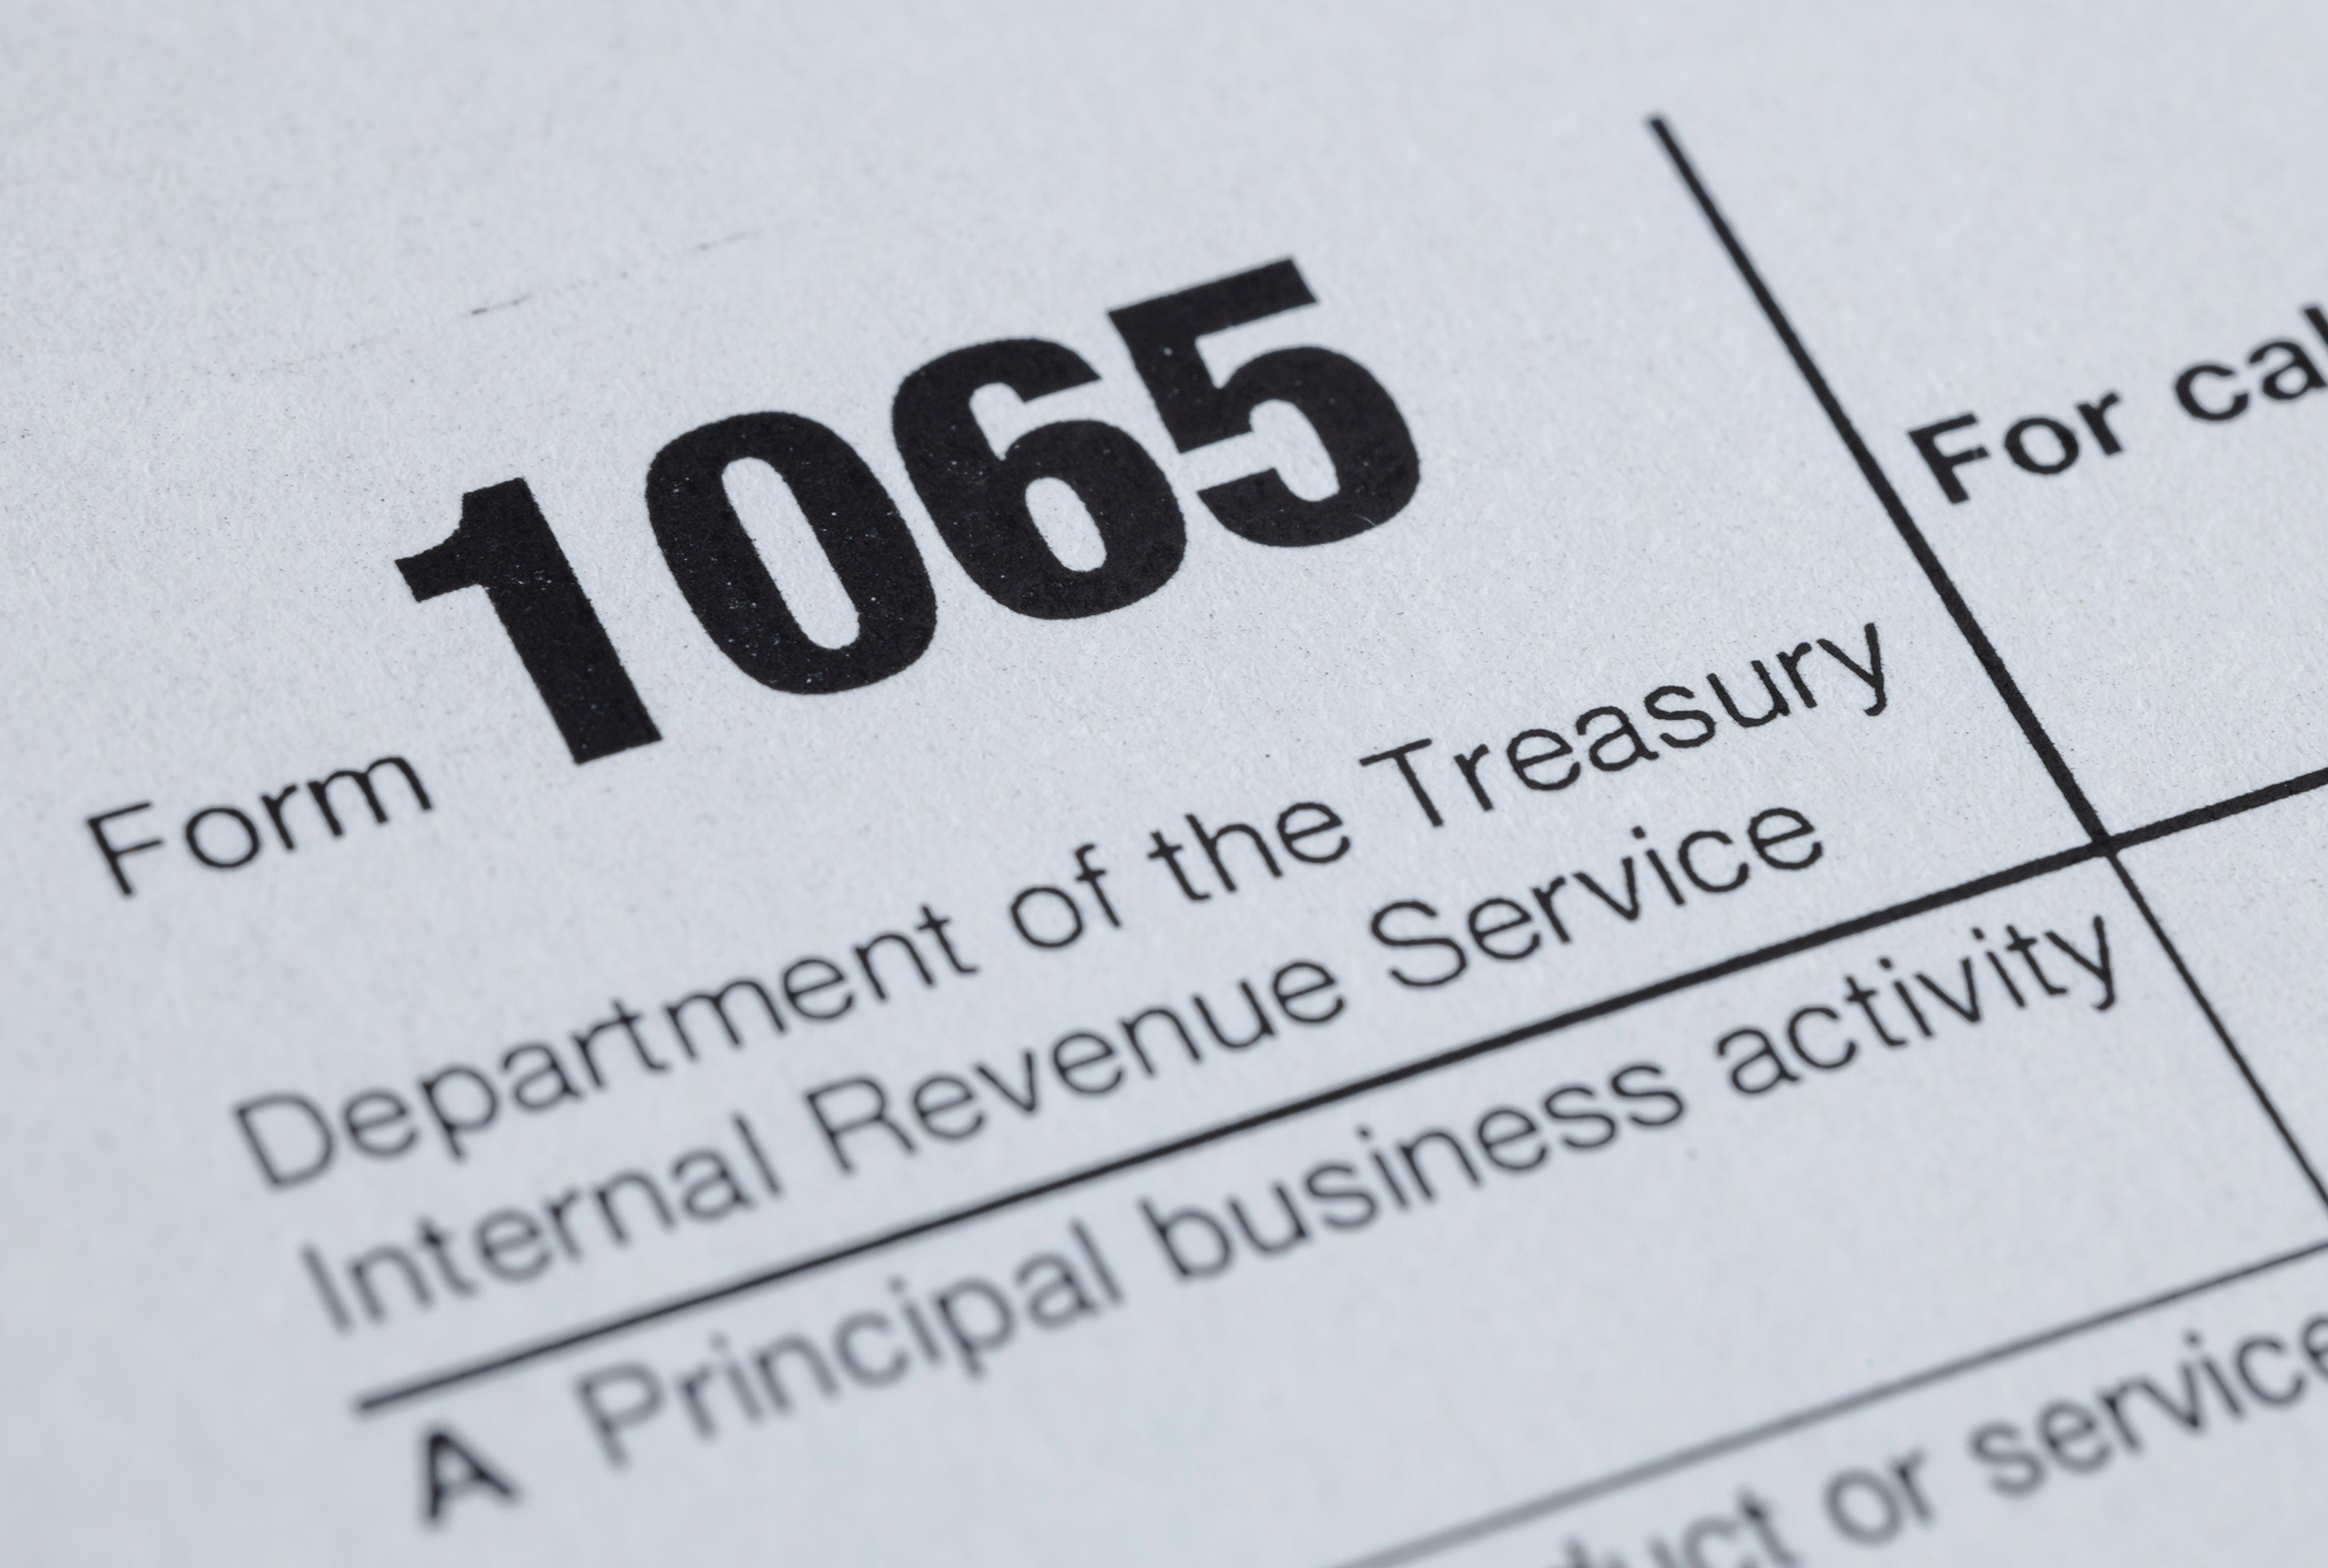
A partnership must file an information return, IRS Form 1065, “U.S. Return of Partnership Income.” On this form, the partnership separately identifies income, deductions, credits and other items.

This allows partners to properly treat items that are subject to limits or other rules that could affect their treatment at the partner level. Examples of items that may require special treatment include capital gains and losses, interest expense on investment debts, and charitable contributions. Each partner receives a Schedule K-1, showing their share of partnership items for the tax year.

Basis and distribution rules ensure that partners aren’t taxed twice. A partner’s initial basis in his or her partnership interest (which varies depending on how the interest was acquired) is increased by his or her share of partnership taxable income. When that income is paid out to partners in cash, they aren’t taxed on the money if they have sufficient basis. Instead, partners reduce their basis by the amount of the distribution. If a cash distribution exceeds a partner’s basis, then the excess is taxed to the partner as a gain.

Heads Up!

Understanding the ins and outs of partnership taxation can help you avoid surprises come tax time. If you’re unsure how these rules apply to your specific situation, especially with complex items such as losses or special allocations, don’t hesitate to reach out. Contact the office for help with the math and whatever other questions you may have.
One Big Beautiful Bill Act / Evolution of AI

One Big Beautiful Bill Act / Evolution of AI

BDO Digital Presentation BDO Digital’s discussion on how emerging technologies are rapidly changing financial processes, decision making, and operations at businesses across the country.Download the Presentation OBBBA Presentation The One Big Beautiful Bill Act of...

Could Bad Debts Lower Your 2026 Taxes?

Could Bad Debts Lower Your 2026 Taxes?

When customers or others don’t pay what they owe your business, you may be able to claim a bad debt deduction to help offset the financial loss. But it isn’t automatic. Businesses must satisfy specific federal tax rules and maintain adequate records to support the...

4 Tax-Smart Investment Moves Before Year End

4 Tax-Smart Investment Moves Before Year End

As the end of 2026 approaches, look beyond investment performance and consider how taxes may affect your overall returns. Although tax considerations generally shouldn’t drive investment decisions, a year-end portfolio review may identify opportunities to reduce your...

Make the Most of Your HSA Tax Benefits

Make the Most of Your HSA Tax Benefits

If you’re eligible to contribute to a Health Savings Account (HSA), consider taking a closer look at your contribution strategy. You may be able to reduce your 2026 taxes while strengthening your long-term financial security. Although many people use HSAs to pay...

Ready Your Books for Tax Season

Ready Your Books for Tax Season

One of the most common bookkeeping mistakes business owners make is mixing business and personal finances. Addressing this issue before year end can simplify tax preparation, improve the accuracy of your financial records and help reduce the risk of IRS questions....